Are you curious about how much auto insurance in Massachusetts is really going to set you back? Buckle up because we’re diving into the world of insurance rates in the Bay State to help you navigate these financial waters like a seasoned pro. Whether you’re a young driver or have decades of experience, understanding the factors that influence your premium can save you big bucks.
Ready to uncover the secrets behind those elusive insurance numbers? In this guide, we’ll break down everything from age and driving history to the type of car you drive and your location within Massachusetts. And don’t worry, we’ve got plenty of tips and tricks up our sleeves to help you snag the best deal possible. Let’s get started!
Factors Affecting Auto Insurance Rates in Massachusetts
Ever wondered why your neighbor pays less for car insurance than you? It might all boil down to variables you wouldn’t expect. Let’s break down the factors that can significantly impact your auto insurance rates in Massachusetts.
Age and Its Impact on Premiums
Your age can dramatically affect your auto insurance costs. If you’re under 25, you’re likely paying more. Why? Statistically, younger drivers are involved in more accidents. BUT, once you hit 25, you’ll probably see your rates drop. It’s all about perceived risk. Young drivers are seen as riskier by insurers.
Driving History Matters
A squeaky-clean driving record can save you big bucks. Speeding tickets, accidents, and DUIs can send your rates skyrocketing. Here’s the deal: insurers use your driving history to predict future behavior. If you’ve been involved in an accident or have traffic violations, expect higher premiums.
Vehicle Type and Its Influence
What you drive affects what you pay. Own a sports car? Get ready for a higher insurance bill. Vehicles like sedans, with excellent safety records, often cost less to insure. Think about this: a flashy car might be fun, but it also comes with a flashy insurance premium.
Location, Location, Location
Where you live in Massachusetts can play a huge role in determining your rates. Urban areas typically mean higher premiums. Why? More cars on the road equals a higher chance of accidents. Pro Tip: If you move from a bustling city to a quiet suburb, you might see your insurance costs drop.
Average Cost of Auto Insurance in Massachusetts
Are you ready to find out how much you’re really spending on auto insurance in Massachusetts? You might think you’re getting a good deal, but the numbers may surprise you.
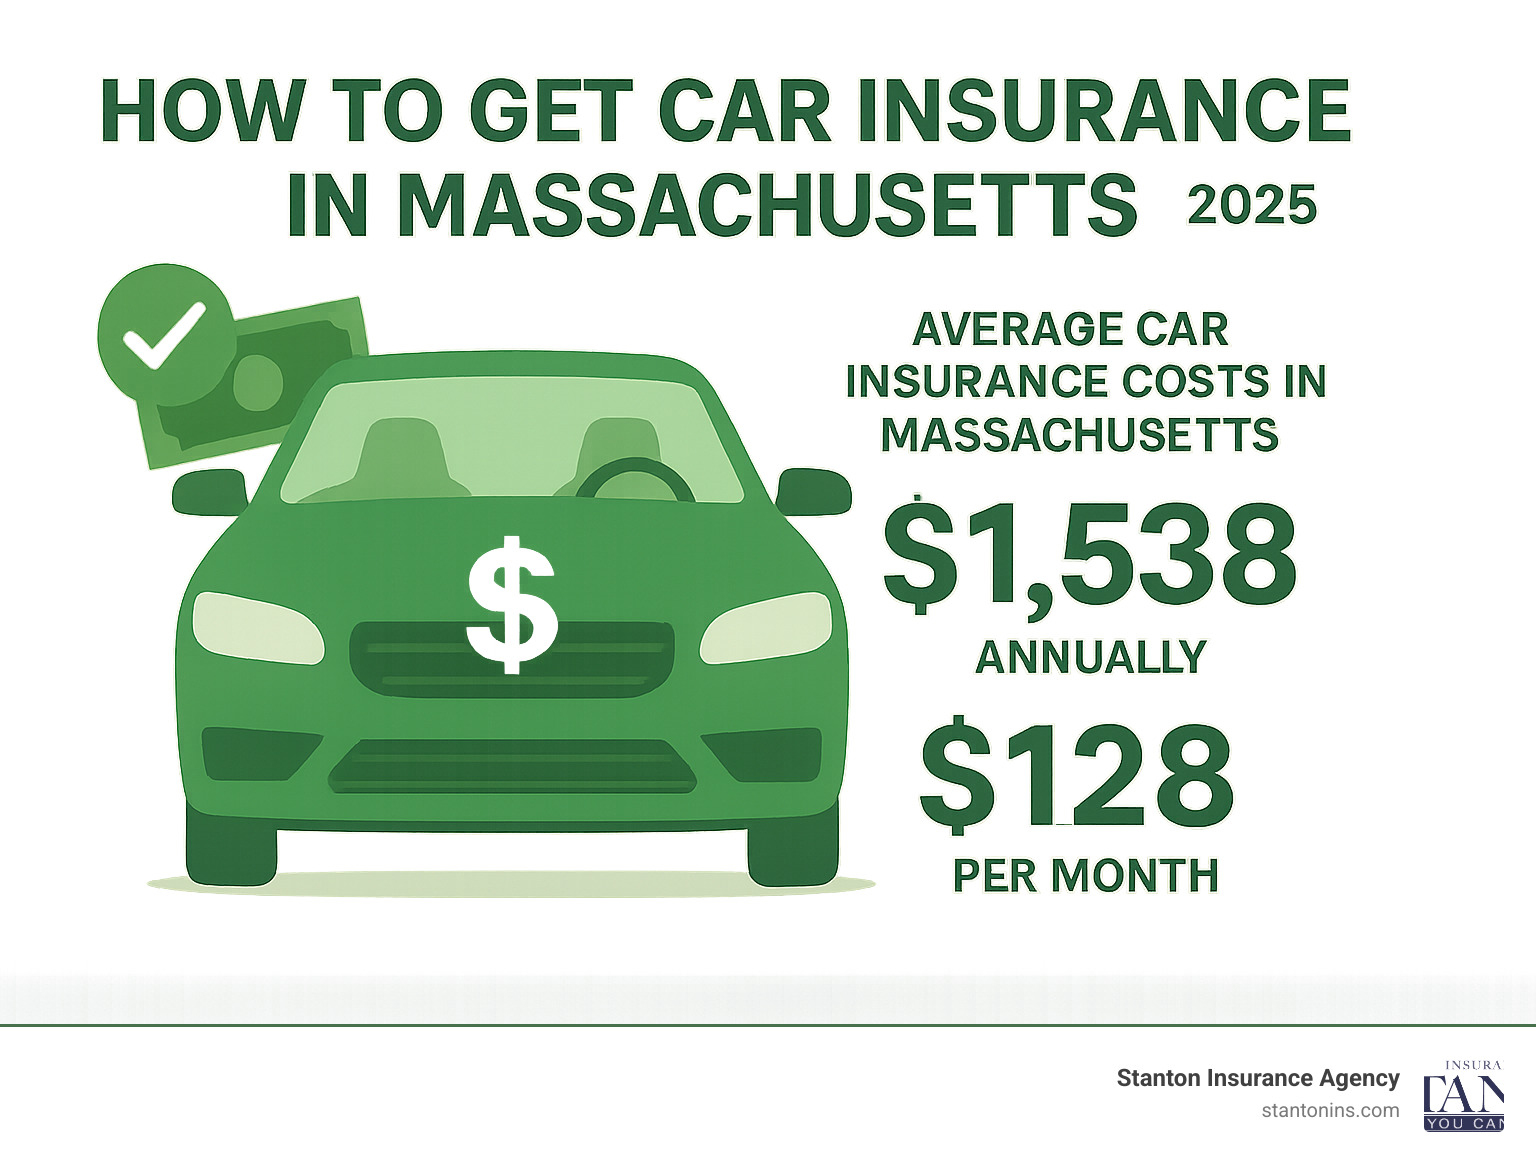
The average annual cost of auto insurance in Massachusetts is around $1,200. That breaks down to about $100 a month. But here’s the deal: these rates can fluctuate wildly based on where you live and who you are.
Comparing Massachusetts Rates to Other States
Massachusetts is not the costliest state, but it’s not the cheapest either. Here’s a quick comparison:
| State | Average Annual Cost |
|---|---|
| Massachusetts | $1,200 |
| New York | $1,500 |
| California | $1,800 |
| Ohio | $900 |
Notice how Massachusetts sits comfortably in the middle. You’re not paying the most, but you’re definitely not paying the least.
Variations in Costs Between Cities in Massachusetts
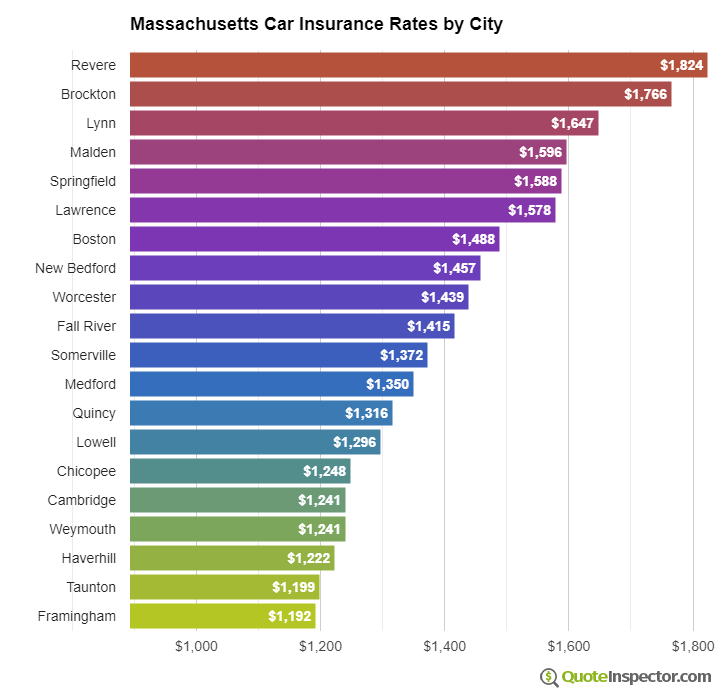
But let’s dig deeper. Different cities within Massachusetts have different rates. If you’re in Boston, expect to pay more due to higher traffic and accident rates. Yet, if you’re in a smaller city like Springfield, your rates could be significantly lower.
- Boston: $1,500 annually
- Worcester: $1,100 annually
- Springfield: $950 annually
The urban hustle comes with an insurance price tag. Living in Boston could mean paying up to 50% more than Springfield residents.
Average Costs by Age Group
Age is just a number, right? Not when it comes to your insurance rates. Here’s how your age impacts your premium:
- Teens (16-19): $3,500 annually
- 20s: $2,000 annually
- 30s-40s: $1,200 annually
- 50s+: $900 annually
Pro Tip: If you’re a teen driver, brace yourself. You’re looking at three times the cost of a seasoned driver in their 50s.
It’s clear: age is a major factor. As you get older, your premiums usually decrease. But youth comes at a cost, so make sure you’re getting all the discounts you can!
Types of Auto Insurance Coverage Available
Did you know that choosing the right auto insurance can save you hundreds, if not thousands of dollars? It’s true! But with so many options out there, picking the best coverage can feel like navigating a maze.
Let’s break down the different types of coverage available in Massachusetts so you can make an informed decision. Trust me, understanding these options can make a world of difference when it comes to protecting your finances and your car.
Common Types of Auto Insurance Coverage
Here’s the deal: there are several types of auto insurance coverage you need to know about. Each serves a different purpose, and having the right mix can protect you from unexpected costs.
- Liability Coverage: Covers damages to other people’s property and bodily injuries you cause in an accident.
- Collision Coverage: Pays for repairs to your vehicle after an accident, regardless of who is at fault.
- Comprehensive Coverage: Protects against non-collision events like theft, vandalism, or natural disasters.
- Personal Injury Protection (PIP): Covers medical expenses and lost wages after an accident, no matter who caused it.
- Uninsured/Underinsured Motorist Coverage: Safeguards you if you’re hit by someone with little or no insurance.
Liability vs. Collision vs. Comprehensive Coverage
Each coverage type serves a unique purpose. Liability insurance is mandatory in Massachusetts and covers others’ damages if you’re at fault. However, it doesn’t cover your own car repairs.
Collision coverage steps in when your vehicle needs repairs from an accident. Comprehensive coverage, on the other hand, kicks in for non-accident incidents like a tree branch falling on your car.
Here’s a quick table to compare:
| Coverage Type | Benefits |
|---|---|
| Liability | Protects you against claims for damages and injuries you cause. |
| Collision | Covers repairs to your vehicle after an accident. |
| Comprehensive | Covers non-collision-related damages. |
What Full Coverage Auto Insurance Includes
Think “full coverage” means every single thing? Not quite, but it’s close! Typically, full coverage is a combination of liability, collision, and comprehensive insurance. It’s designed to offer maximum protection for your vehicle.
Full coverage may also include PIP and uninsured motorist protection. This combination ensures you’re protected from almost any angle.
Pro Tip: Always review your policy details. Full coverage might not cover every scenario, but it’s a strong shield against most common risks.
Discounts and Ways to Save on Auto Insurance
Want to slash your auto insurance bill in Massachusetts? You’re in luck! There are several ways to save big on your premiums.
It’s not just about finding the right provider. Knowing the discounts available can make a huge difference in what you pay. Let’s dive into the strategies that can help keep more money in your pocket.
Common Discounts Offered by Insurers in Massachusetts
Many insurers offer a range of discounts that can lower your premiums. If you’re a safe driver with no claims, you’re in a good position to start saving. Other common discounts include multi-car discounts for households with more than one vehicle, and loyalty discounts for staying with the same insurer over time. These can cut your rates significantly.
Bundling Policies for Maximum Savings
Looking to save even more? Consider bundling your auto insurance with other policies, like home or renters insurance. This can lead to substantial savings. Insurers love when you purchase multiple policies from them, and they’re often willing to give you a better deal.
Pro Tip: Always ask your insurer about bundling discounts. You might be surprised at how much you can save!
Maintaining a Good Driving Record
Here’s the deal: A clean driving record is your ticket to lower insurance rates. Avoid speeding tickets and accidents, and you’ll likely see your premiums drop. Insurers reward safe drivers with lower rates because they’re less risky to insure. Defensive driving courses can also help keep your record spotless and sometimes qualify you for additional discounts.
Impact of Increasing Deductibles on Insurance Rates
Want to lower your monthly premium? Increasing your deductible could be the answer. BUT, there’s a trade-off: you’ll need to pay more out of pocket in the event of a claim. It’s crucial to weigh the savings on your premium against the potential cost if you need to file a claim. A higher deductible can lead to significant savings on your premium, but only if you can afford the potential expense.
Legal Requirements for Auto Insurance in Massachusetts
Are you driving legally in Massachusetts? You might be surprised by the state’s auto insurance requirements. Let’s dive into what you need to stay on the right side of the law.
Massachusetts takes auto insurance seriously. The state has set minimum coverage requirements to ensure that all drivers are financially responsible on the road. It’s not just about having any insurance; it’s about having the right coverage to protect yourself and others.
Minimum Insurance Requirements Set by the State
Every driver in Massachusetts must meet specific insurance requirements. Here’s what you’re legally required to have:
| Coverage Type | Minimum Limit |
|---|---|
| Bodily Injury to Others | $20,000 per person / $40,000 per accident |
| Personal Injury Protection (PIP) | $8,000 per person |
| Bodily Injury Caused by Uninsured Auto | $20,000 per person / $40,000 per accident |
| Damage to Someone Else’s Property | $5,000 per accident |
If you don’t meet these minimum requirements, you’re not just risking your wallet—you’re risking your license. The consequences include fines, license suspension, and registration revocation.
Consequences of Not Meeting Legal Requirements
Think skipping insurance is no big deal? Think again. Driving without the required insurance in Massachusetts can lead to serious penalties. You’ll face fines ranging from $500 to $5,000, possible jail time, and an increase in insurance premiums when you do get coverage.
Massachusetts isn’t playing around. The state enforces its financial responsibility laws to make sure all drivers can cover costs in case of an accident. This means having the right insurance isn’t just smart—it’s mandatory.
Pro Tip: Always carry proof of insurance in your vehicle. It’s your ticket to proving you’re covered, anytime, anywhere.
Choosing the Right Insurance Provider
Did you know that choosing the wrong insurance provider could cost you hundreds of dollars more each year? Picking the right one isn’t just about the price tag.
Sure, price matters, but what about customer service and financial stability? You need an insurer that backs you up when you need it most.
Factors to Consider When Selecting an Insurance Provider
Before you sign up, compare the customer service ratings of different providers. After all, you don’t want to wait on hold during an emergency. Financial stability is another biggie. Can they pay out when disaster strikes? Here is the deal: You want a provider who’s been around the block and isn’t going anywhere anytime soon.
Comparing Customer Service Ratings
Let’s dive into the data. Here’s how major insurers stack up when it comes to keeping their customers happy:
| Insurance Provider | Customer Service Rating |
|---|---|
| Provider A | 4.5/5 |
| Provider B | 4.2/5 |
| Provider C | 3.8/5 |
Importance of Financial Stability and Claims Handling
A financial nightmare is realizing your provider can’t cover your claim. Choose a provider with a strong financial rating from agencies like A.M. Best. Claims handling is crucial too. You want hassle-free claims with quick payouts.
How to Evaluate Policy Terms and Conditions
Policy terms can be confusing. But here’s a trick: Look for any hidden fees or exclusions. Pro Tip:
Always read the fine print and ask questions if anything is unclear.
Knowing exactly what’s covered will save you headaches down the road.
Summary
So there you have it! From understanding the key factors that impact your insurance rates to knowing how to pick the right coverage, you’re now armed with the knowledge to tackle the Massachusetts auto insurance market. Remember, a little research goes a long way in securing a policy that suits your needs without breaking the bank. Drive safe, and may the odds be ever in your favor!
Q&A
What factors influence auto insurance rates in Massachusetts?
Factors include your age, driving history, the type of vehicle you drive, and your location within the state.
How much is the average cost of auto insurance in Massachusetts?
The average annual cost is around $1,200, while the monthly cost hovers around $100, though this can vary based on several factors.
What types of auto insurance coverage should I consider?
Common types include liability, collision, comprehensive, and full coverage, each offering different levels of protection.
Are there discounts available for auto insurance in Massachusetts?
Yes, insurers offer discounts for things like a good driving record, bundling policies, and even having certain safety features in your car.
What are the legal requirements for auto insurance in Massachusetts?
The state requires minimum liability coverage, including bodily injury and property damage, among others.
How can I choose the right insurance provider?
Consider factors such as customer service ratings, financial stability, claims handling, and the specific policies and terms they offer.
